Key takeaways for Q3 2026
Headline funding rose 28%, but deal activity weakened
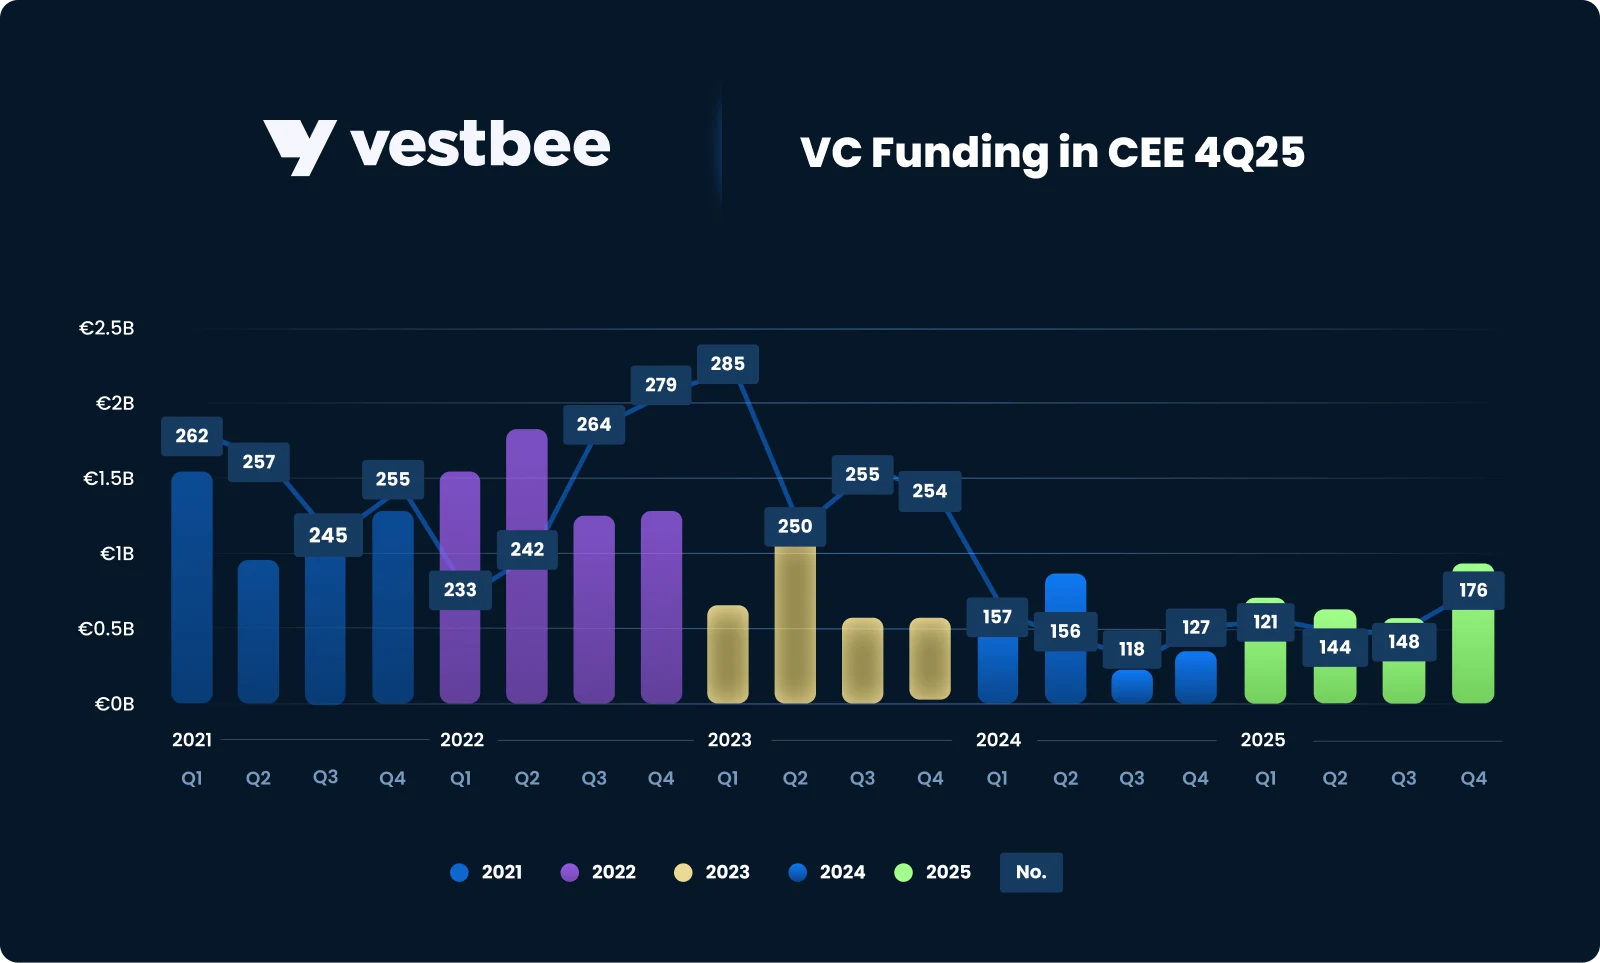
CEE startups raised approximately €632 million in Q3 2026, up 28% from Q2 (€495 million) and 24% from Q3 2025 (more than €510 million). The number of rounds followed the opposite trend: falling to 118 from 143 in Q2 and 148 in Q3 2025.
In Q3 2026, investment volume was driven by two large rounds: EnduroSat, with €186 million raised, and Oxylabs, with €118 million, which together took 48% of the quarter. The same pattern can be seen in previous quarters — the largest rounds drove overall funding figures, while the rest of the market remained flat or declined slightly.
Bulgaria and Lithuania took 62% of the capital, mainly across three rounds
Bulgaria (€200.6 million across 7 rounds), and Lithuania (€192.0 million across 13 rounds), together absorbed 62% of regional funding. Poland recorded 48 rounds but attracted only €93.0 million, or 15% of Q3 total funding. Romania (€55.2 million), Estonia (€23.1 million), Ukraine (€21.2 million), and Serbia (€20.1 million) followed.
The largest rounds were led by investors from outside the region
US venture capital funds Riot Ventures and Atreides Management co-led €186.4 million round for EnduroSat. Warburg Pincus, US private equity firm, invested €118.2 million in Oxylabs, becoming the company’s first outside investor since its founding in 2015.
The European Bank for Reconstruction and Development (EBRD) participated in two of CEE’s ten biggest deals: Ominimo's Series B and a minority equity investment in Sportano. Only one of the ten largest rounds was led by a CEE-focused fund — TCEE Fund IV, advised by 3TS Capital Partners, which led €9.1 million Series A for Tiger Technology.
This picture reflects the largest deals rather than the market as a whole. CEE-focused funds remain dominant in smaller rounds, as the list of most active investors will show below.
CEE-rooted companies building abroad
Six of the region’s largest funding rounds involved companies with CEE roots but headquartered abroad — in the US, UK or Germany: Pathway (Palo Alto), CUBE3 AI (Palo Alto), FintechOS (London), Tiger Technology (Georgia, US), Immersion Labs (Arizona, US) and F13 (Berlin). Together, they accounted for approximately €114 million, or 18% of the total Q3 funding.
Global VC in Q3 2026: AI took 64%, but the quarter cooled
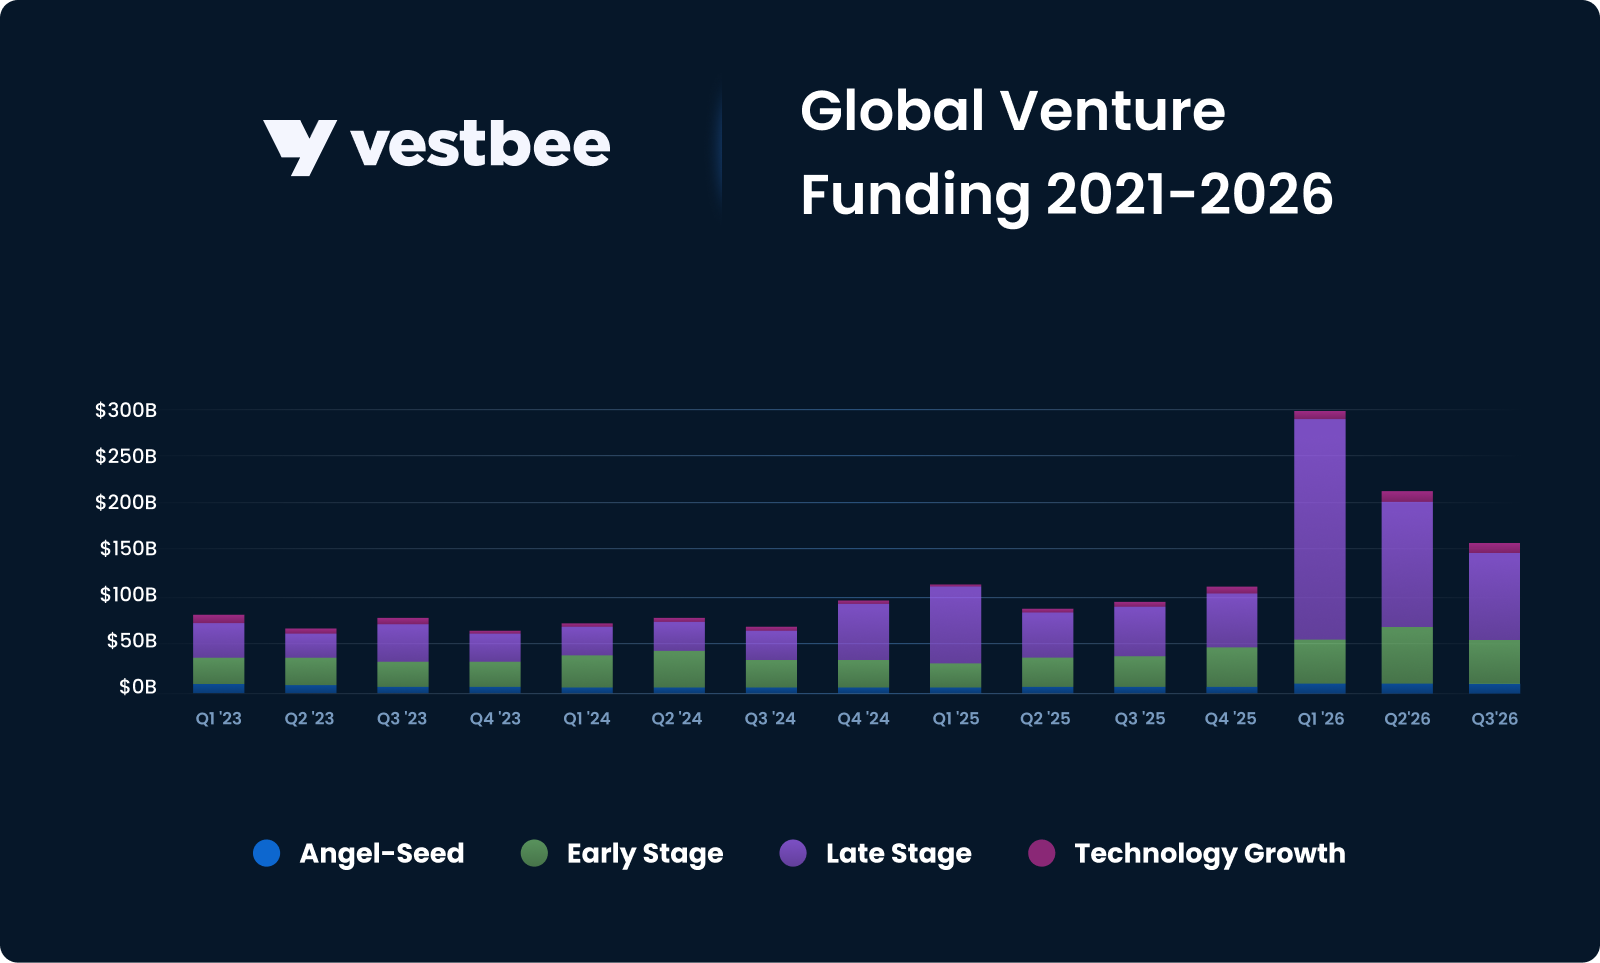
In Q3 2026, global venture funding reached $159 billion, down 25% from $212 billion in Q2 and up 53% from $104 billion a year earlier, according to Crunchbase. Around a third of all that capital went to those 27 companies, which closed billion-dollar-plus rounds. The largest funding deals went to Databricks and Safe Superintelligence, which secured $5 billion each. At the same time, 64% of the total Q3 global venture funding went to AI startups.
Geographically, US companies captured the lion’s share of funding, attracting $91 billion, or 57% of the total. By stage, late-stage funding reached $105 billion, early-stage — $40.6 billion, and seed — $13 billion.
The IPO window stayed open
Completed listings included ChangXin Memory Technologies (about $8.6 billion raised in total at an $85.5 billion valuation), Enflame ($912 million at $25.5 billion), Bending Spoons ($1.6 billion at $18.4 billion), Unitree Robotics ($905 million at $9 billion), and Shein (listed at $26.3 billion).
Crunchbase also lists three large acquisitions, none of which we count as a completed exit: Nvidia's reported $12.9 billion agreement to buy Hugging Face has not been confirmed by the companies, AMD's $8.2 billion all-stock deal for World Labs is expected to close by the end of 2026, and Stripe confirmed acquisition of OpenRouter, which price ($7.5 billion reportedly) was not disclosed by the companies.
Vestbee view: Q3 was a weaker quarter globally than Q1 ($305 billion) and Q2 ($212 billion) but stronger than Q3 2025 ($104 billion). For CEE, the key signal is that rising investment volumes don’t necessarily indicate a healthier VC market. Capital remains concentrated in large rounds, while VC funds still depend on successful exits to realise returns.
Europe: up YoY, flat QoQ — CEE grows more slowly
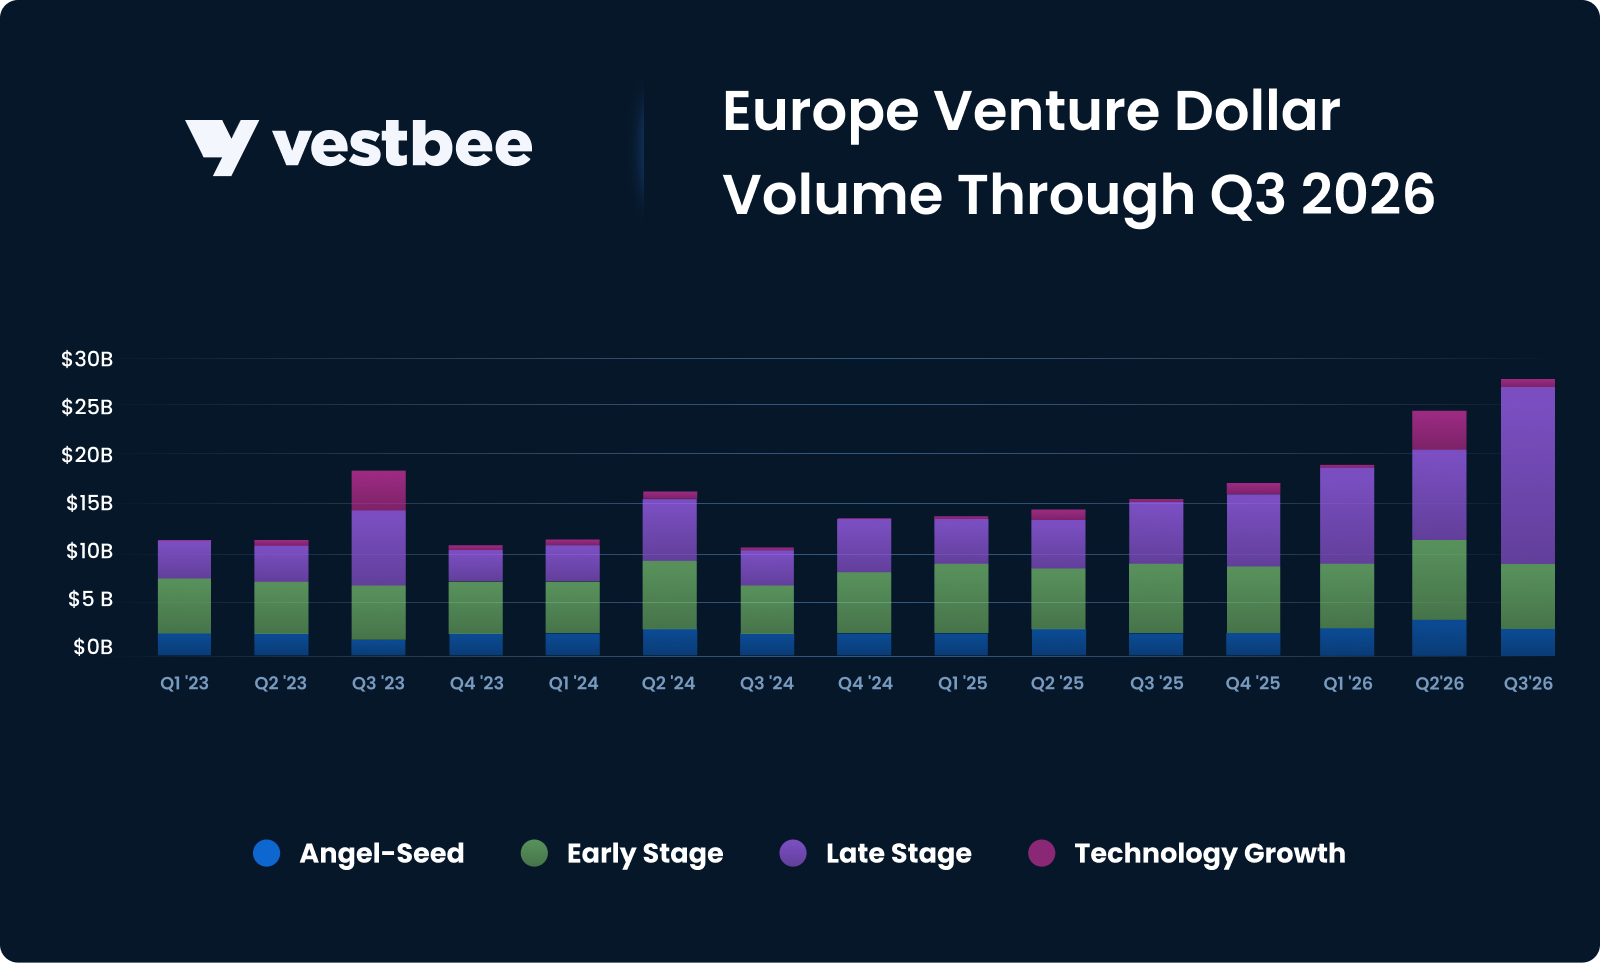
European startups raised $25 billion in Q3, up approximately 4% in Q2 ($24 billion) and 77% in Q3 2025 ($14 billion), according to Crunchbase. The total funding raised in Europe accounted for 16% of global investment volume.
The UK led with $7.5 billion, followed by Germany ($5 billion), France ($4.8 billion), Sweden ($1.5 billion), the Netherlands ($1.4 billion), and Spain ($1.2 billion).
Late-stage funding reached $17.3 billion (70% of the total, across 83 companies), early-stage — $5.7 billion and seed — approximately $2 billion across more than 750 companies.
AI companies took the biggest slice — $18.8 billion, or 75% — of the funding pie. The largest rounds were closed by Mistral ($3.5 billion), Nscale ($3.36 billion convertible note), Helsing ($1.8 billion), and Quantum Systems ($1.2 billion).
Where CEE sits
CEE startups raised €632 million ($695 million) in Q3, accounting for 2.8% of total European VC funding. This was up from around 2% in Q2, but still below 5% recorded in Q1, according to Vestbee’s data. Year-on-year, CEE funding grew by less than 24%, compared to 77% across Europe.
Two large rounds accounted for much of CEE’s funding. Without EnduroSat and Oxylabs, the region would have raised approximately $360 million, representing just 1.4% of European funding.
Across Europe, growth was largely driven by AI and $100 million-plus rounds, while CEE's two largest deals were in space hardware and data infrastructure.
Note: These shares are approximate, as Vestbee and Crunchbase use different data collection methods.
VC investment trends in CEE
Reading Q3 2026 in cycle terms
Over the past five quarters, CEE funding has fluctuated between approximately €495 million and €860 million. In Q3 2026, startups raised €632 million across 118 rounds — the lowest deal count in this period.
While total funding increased compared to Q2 (€495 million), the number of rounds declined (from 143), reflecting growing influence of a few large deals on overall investment volumes. However, the Q3 deal count may still increase as previously undisclosed rounds are reported.
Three trends defined Q3 2026:
- Large rounds of €100 million+ set the headline again. EnduroSat and Oxylabs together accounted for 48% of total funding, compared to the two largest rounds of 47% in Q1 and 34% in Q2. Including CUBE3 AI, the three largest deals represented 55% of Q3 total. Nine rounds reached or exceeded €10 million, compared to seven in Q2 and ten in Q3 2025.
- Poland recorded more deals but raised less capital. The number of rounds increased from 44 in Q2 to 48 in Q3, while total funding declined from €140 million to €93.0 million. According to PFR Ventures and Inovo.vc, 37 of these transactions were seed rounds, with a median deal size of approximately €1.1 million (PLN 4.6 million). Public and public-private capital accounted for 54% of total funding, while deals involving international funds represented 55%, despite making up only 11 of the 48 transactions. These categories overlap.
- The gap between mo-sized and mega-rounds persisted. CEE recorded six rounds between €10 million and €30 million, but only one between €30 million and €100 million — CUBE3 AI. Vestbee’s Q2 report pointed to the similar pattern in growth-stage capital, suggesting that large growth-stage deals remain relatively rare in the region.
Vestbee view: Q3 saw higher funding volumes but fewer deals. Just three rounds — EnduroSat, Oxylabs, and CUBE3 AI — accounted for 55% of total funding, while the number of rounds fell 17.5% quarter-on-quarter. The median disclosed round was around €1.4 million, highlighting the prevalence of smaller deals in CEE.
One potential mega-round could significantly impact CEE’s funding figures in Q4. In September, Bloomberg reported that Uforce, the Ukrainian-British drone manufacturer, was in talks to raise $500 million in a Series A led by Valor Equity Partners at a valuation of approximately $5 billion. As the round had yet not closed, it was excluded from our Q3 figures. If completed in Q4, it could become the largest round recorded in our five-quarter dataset.
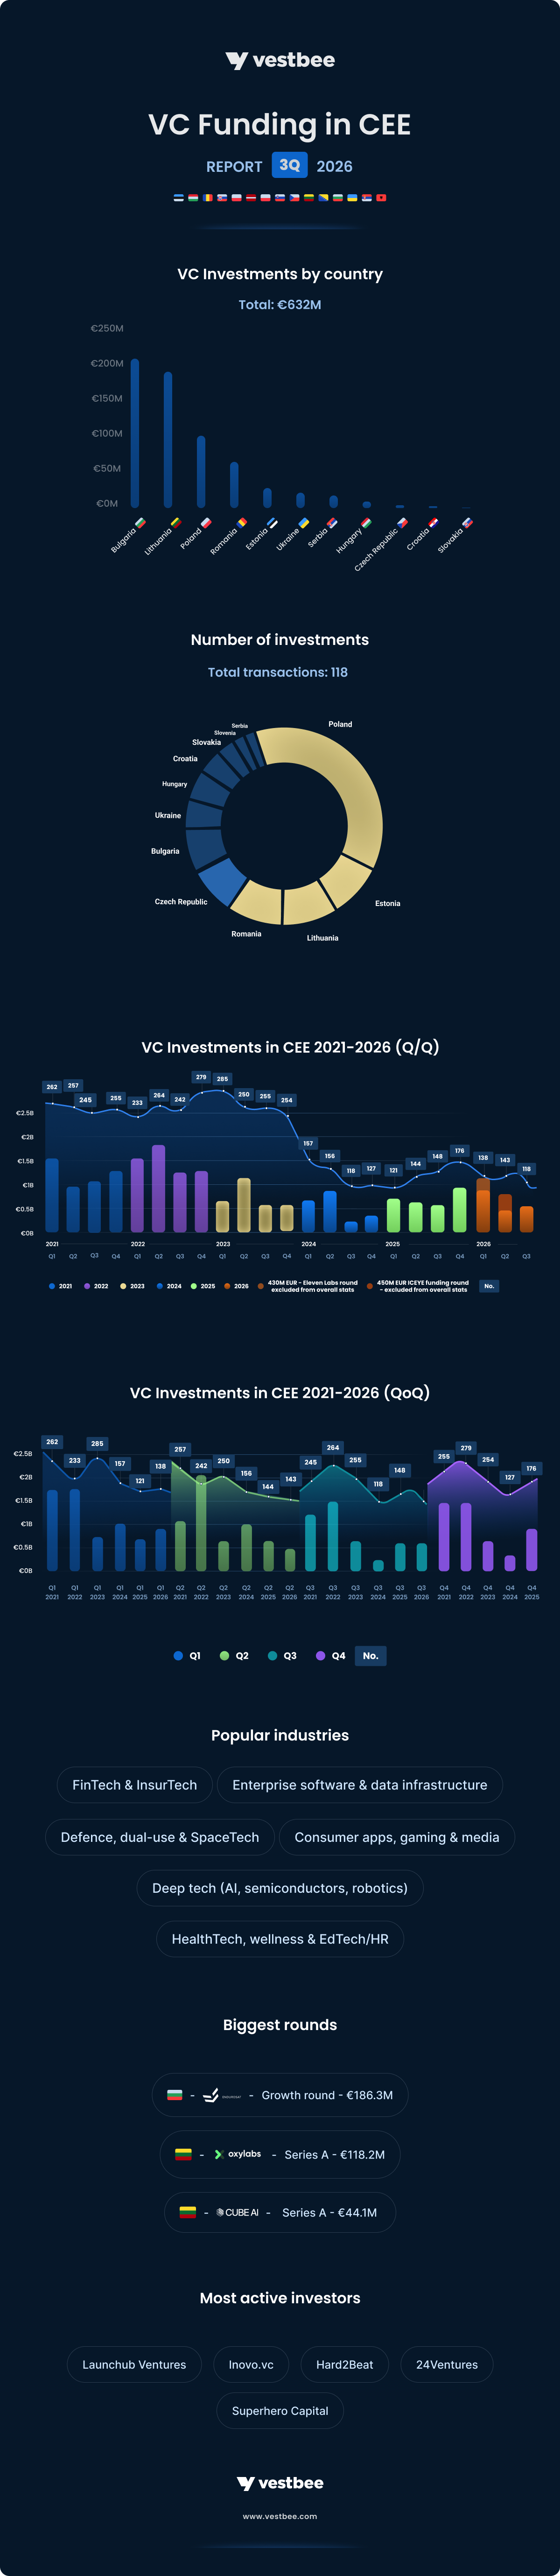
Startup investment rounds in CEE in Q3 2026
- Number of funding rounds: 118 (89 fully disclosed)
- The biggest disclosed rounds: EnduroSat — €186.4M; Oxylabs — Series A — €118.2M; CUBE3 AI — Series A — €44.1M
- Total value of funding closed in CEE: approximately €632M
- Countries with the highest number of rounds: Poland — 48, Estonia — 13, Lithuania — 13
- Countries with the highest total capital raised: Bulgaria — €200.6M, Lithuania — €192.0M, Poland — €93.0M
- Most active VC funds: LAUNCHub Ventures, Inovo.vc, Hard2beat, 24Ventures, and Superhero Capital
- Most popular industries: fintech & insurtech, enterprise software & data infrastructure, defence, dual-use & spacetech, consumer apps, gaming & media, deeptech (AI, semiconductors, robotics), healthtech, wellness & edtech/HR
- Not included in the totals: Uforce (Ukraine-UK) is reportedly in talks to raise $500M Series A
What shaped the CEE ecosystem in Q3 2026
Bulgaria and Lithuania: 62% of region’s funding across three rounds
EnduroSat’s round accounted for around 93% of Bulgaria's quarterly total funding. In Lithuania, Oxylabs represented around 62% of the country’s total investment volume, and, with CUBE3 AI’s €44.1 million Series A, it reached around 85%.
EnduroSat's round was co-led by Riot Ventures and Atreides Management; GV, Founders Fund, Lux Capital, House Capital, Omnes Capital, Giant Ventures, Emphatic Capital, the EIC Fund and Endeavor Catalyst also took part. The company builds satellites and satellite subsystems.
Oxylabs' investment came from the Capital Solutions Founders Fund, managed by Warburg Pincus, which does hybrid capital transactions; the announcement does not specify the instrument or the split between new capital and secondary shares.
Tiger Technology, a Bulgarian software company, raised a $10 million Series A led by TCEE Fund IV, advised by 3TS Capital Partners, with TDJ, Endeavor Catalyst and Impetus as new investors.
Poland: 41% of the rounds, 15% of the capital
Poland recorded 48 funding rounds in Q3, up from 44 in Q2, while total investment declined by 34% to €93 million. According to PFR Ventures and Inovo.vc, 37 transactions were at the pre-seed or seed stage, with a median round size of approximately €1.1 million. Public and public-private capital participated in deals accounting for 54% of total investment.
Among the notable transactions were Pathway's newly announced $30 million funding, Sportano's €15 million equity investment from the EBRD, and Immersion Labs' €4.5 million round led by Axon. Defence tech startup DefendEye also attracted investment from US-based In-Q-Tel, alongside Hard2beat, NovaCapital, and ffVC.
Vestbee view: Poland remains CEE’s most active market by deal count, but not by investment volume. Early-stage investment dominated, while large rounds remained rare. The two largest deals involved Palo Alto-based Pathway and EBRD-backed retailer Sportano, but neither came close to Q2’s $75M Series A for Viktor. Looking ahead, the key question is whether Poland’s early-stage startups can attract the follow-on funding needed to scale.
Romania, Serbia, and Hungary: fintech, insurtech, and data infrastructure
Romania attracted €55.2 million in Q3, with nearly 80% coming from just two rounds. FintechOS secured €25.5 million in equity and debt financing from Bek Ventures, IFC, Cipio Partners and Molten Ventures, and Santander CIB. Meanwhile, Veridion raised €18.2 million Series A led by Hoxton Ventures, with participation from existing investors.
In Serbia, AI-powered motor insurance company Ominimo raised €20.1 million Series B round, backed by investors including the EBRD. The deal valued the company at a reported $1.6 billion, making it Serbia's first unicorn.
Hungary recorded six rounds totalling €11.5 million, with BOOKR Kids' €6.1 million Series A, led by TCEE Fund IV, advised by 3TS Capital Partners, accounting for more than half of total.
Ukraine: funding rises, deal count falls
Ukrainian startups raised €21.2 million across 7 rounds, up 30% from €16.3 million in Q2, despite the number of rounds failing from 16.
Yope's €11.2 million seed round, led by Northzone with participation from Inovo.vc, Redseed and Geek Ventures, accounted for approximately 53% of the total. Other notable deals include Occam Industries (€3.8 million) and London-based, Ukrainian-founded Embedd (€2.5 million).
Space and defence: one large round, many small ones
In Q3 2026, space tech raised approximately €190 million, accounting for 30% of total CEE funding. Nearly all of this came from EnduroSat, while Lithuanian Blackswan Space (€2.6 million) and Croatian Genesis Space Flight Laboratories (€1.1 million) together raised much smaller rounds.
Defence and dual-use startups also raised investment, although disclosed rounds remained relatively small. Among them were Occam Industries (€3.8 million), DOD Solution (€1.9 million), and Trinity Robotics (€0.5 million).
Meanwhile, defence-focused VC firm Expeditions closed its second fund at €197 million in July. This reflects a broader trend in 2026: while disclosed rounds for defence and dual-use startups in CEE remain relatively small, investors are raising substantial capital for those industries.
Which other specialised VC firms back defence tech and dual-use startups in Europe? Check out Vestbee’s full list of defence and dual-use investors with detailed information on their current funds and investments strategies.
AI as the default positioning
Around a third of 50 companies that closed notable funding rounds in Q3 2026 (see the list below) positioned themselves as AI products or AI infrastructure. These range from Pathway's post-transformer models and F13's vector-graphics models to semiQa's analog AI chips and a wide range of vertical applications, including Hellobot, TesterArmy, ElredoVoice, Guideless, bilt.me, Kyndred, and display.dev.
Of the 17 AI-focused companies that disclosed funding amounts, 12 raised less than €2.5 million, and only five secured €4 million or more: Pathway, CUBE3 AI, Ominimo, Immersion Labs, and F13. The cohort is spread across at least five countries.
Scoring our Q2 outlook
We made five predictions for CEE last quarter. Here is what we’ve got:
- Defence deal flow rises, with at least one €40 million+ round — miss on a narrow reading. Q3 didn’t bring defence-focused rounds of that size. The largest disclosed deals included Occam, DOD Solution, and Trinity Robotics. We didn’t count EnduroSat here, as it is classified as a space tech company. Uforce, which was reportedly in talks for a $500 million raise, has announced a close yet.
- US early-stage entry spreads beyond Poland — miss on the evidence in our data. In Q3, the US growth capital from Riot, Atreides, GV, Founders Fund, and Warburg Pincus was poured into Bulgarian and Lithuanian companies. At seed, US investors, including Y Combinator, In-Q-Tel, and Axon, preferred the Polish market. There was no disclosed participation from the US backers in the seed deals across Czechia, Lithuania, Latvia, Estonia, or Ukraine.
- Ukraine sees growth in funding, not just deal activity — partial hit. Ukrainian startups raised €21.2 million across 7 rounds in Q3, with Yope accounting for 53% of the quarter’s investment volume. In comparison, in Q2, the total funding reached €16.3 million across 16 rounds.
- A CEE-rooted company competes for an exit — cannot be assessed. Our dataset does not track exits. According to BADideas.fund, CEE recorded 21 venture-backed exits in the first nine months of 2026 against 38 a year earlier.
- Q2 seed figures are revised upward — cannot be assessed. Our Q3 dataset still shows 143 rounds and €494.9 million in funding for Q2, with no changes visible in the overall figures.
Overall, two predictions missed (one under a strict interpretation), one was partially correct, and two could not be assessed. We expected Q3 to look more like Q2 than Q1, with no obvious nine-figure candidate in sight; two rounds above €100 million arrived, so the headline did not track mid-market flow. Excluding the largest rounds, Q3 was between flat and 17% below Q2, depending on the definition (see Key takeaways).
New VC funds investing in CEE in Q3 2026:
- Expeditions Fund II — final close at €197 million, more than double its initial target; first close was €100 million in October 2025. The Warsaw- and London-based fund invests in early-stage defence and dual-use companies. New limited partners include BAE Systems, Keysight and the EIF; the NATO Innovation Fund and the Polish Development Fund are existing investors.
- Orbit Capital Venture Debt Fund II — second close at €107 million, above the €100 million target; the first close was €70 million in June 2025. The fund provides post-Series A debt in €3-15 million tickets; PFR Ventures joined as a new limited partner with €10 million.
- Nucleo Ventures (formerly Fortech Ventures) — €34 million fund launched at the start of July for early-stage startups and SMEs in Romania and the wider CEE region, backed by the North-West Regional Development Agency through an EU-co-financed programme.
- Resist.UA — second fund targeting up to €50 million in capital commitments, announced on 21 July, for Ukrainian and Ukrainian-rooted defence and dual-use companies.
- Final Frontier and Myriad Venture Partners — Final Frontier Fund II, announced on 21 September with a target of €100 million for pre-seed and seed defence tech in the New Nordics and Ukraine.
After quarter-end: on October 1, DIG Ventures reported the close of its third fund at $120 million. The fund targets European pre-seed and seed companies, mainly in AI-native enterprise and cloud infrastructure. Tt has no CEE-specific mandate, and the type of close was not stated.
Our Q3 funds roundup also lists pan-European funds without a CEE focus, among them Highland Europe (€1.1 billion, closed), White Star Capital ($250 million, final close), Index Ventures ($2 billion raised), Accel ($800 million raised) and Claret Capital (€575 million raised).
Vestbee view: our Q2 report pointed to a shortage of growth-stage capital and the need for more defence tech investment. In Q3, Expeditions closed its €197 million fund for early-stage defence startups, while Orbit Capital secured €107 million for its venture debt fund, targeting post-Series A companies. These developments expand funding options for startups, but do not directly address the shortage of Series B equity funding in CEE.
Now to the month-by-month read. Summary is prepared based on fully disclosed rounds (in terms of value, type and date).
Investment rounds in July 2026
- Number of funding rounds: 38
- The biggest investment rounds: Oxylabs — Series A — €118.2M; Ominimo — Series B — €20.1M; Yope — seed — €11.2M
- Total value of funding secured in CEE: approximately €222M
- Countries with the most rounds: Poland — 8, Ukraine — 5
- Most active VC funds: Inovo.vc, Simpact, 24Ventures
- Most appreciated industries: enterprise software & data infrastructure, consumer apps & energy retail, fintech & insurtech, heathtech & HR, defence & spacetech
July recorded the most rounds (38), accounting for 32% of the quarter’s total funding.
Oxylabs alone represented 53% of July’s funding, securing €118.2 million from Warburg Pincus. The Vilnius-based web-data company was followed by Ominimo's €20.1 million Series B and Yope's €11.2 million.
Poland led by deal count with eight rounds, including Pstryk's €7 million Series A backed by Future Energy Ventures, Axpo, Montis, ffVC, and Simpact. Ukraine recorded five rounds.
Find out more: Top CEE funding rounds closed in July.
Investment rounds in August 2026
- Number of funding rounds: 21
- The biggest investment rounds: CUBE3 AI — Series A — €44.1M; Pathway — seed — €26.7M; BOOKR Kids — Series A — €6.1M
- Total value of funding secured in CEE: approximately €110M
- Countries with the most rounds: Lithuania — 5, Estonia — 4
- Most active VC funds: no fund recorded more than one deal in the month
- Most appreciated industries: enterprise software & AI tooling, consumer apps & gaming, healthtech & edtech, fintech (fraud prevention), deeptech (AI models)
August was the quietest month of Q3 in terms of both deal count and investment volume.
CUBE3 AI's €44.1 million Series A accounted for 40% of the month's recorded funding. Other notable rounds included BOOKR Kids’s €6.1 million Series A in Hungary and Friendly Fire’s €4 million round in Croatia.
Find out more: Top CEE funding rounds closed in August.
Investment rounds in September 2026
- Number of funding rounds: 30
The biggest investment rounds: EnduroSat — €186.4M; FintechOS — combined equity and debt — €25.5M; Veridion — Series A — €18.2M - Total value of funding secured in CEE: approximately €268M
- Countries with the most rounds: Poland — 8, Estonia — 5
- Most appreciated industries: enterprise software, fintech & insurtech, defence & dual-use, spacetech, deeptech (AI, semiconductors), healthtech, wellness, retail
September delivered 42% of the quarter's funding volume across 30 rounds.
Bulgarian satellite company EnduroSat captured 69%, the lion’s share, of the month investment volume, raising a€186.4 million round.
Romanian startups FintechOS (€25.5 million of combined equity and debt) and Veridion (€18.2 million Series A) followed, totaling €44.1 million.
Estonia attracted €20.6 million across 5 rounds, with the largest deals closed by Mesh Wallet and Creem.
Other notable deals included DOD Solution's €1.9 million defence tech pre-seed round, Y Combinator-backed TesterArmy, and drone detection startup DefendEye, backed by In-Q-Tel.
Find out more: Top CEE funding rounds closed in September.
Now, let’s take a closer look at the most interesting CEE startups that closed rounds between July and September 2026.
Most interesting funding rounds in Q3 2026:
- EnduroSat (Bulgaria) — builder of small satellites, satellite subsystems and space services, headquartered in Sofia.
- Oxylabs (Lithuania) — provider of proxy networks and web-data collection infrastructure.
- CUBE3 AI (Lithuania) — AI-based platform for fraud and financial-crime prevention.
- Pathway (Poland) — developer of a post-transformer architecture for frontier AI models.
- FintechOS (Romania) — software platform for designing and launching banking and insurance products.
- Ominimo (Serbia) — AI-driven motor insurance provider.
- Veridion (Romania) — company-data provider offering API access to firmographic data on businesses worldwide.
- Sportano (Poland) — online retailer of sporting goods, based in Zielona Gora.
- Yope (Ukraine) — photo-sharing app built around close friends rather than public feeds.
- Mesh Wallet (Estonia) — non-custodial wallet for gasless USDT transfers.
- Tiger Technology (Bulgaria) — hybrid-cloud data management software.
- Pstryk (Poland) — electricity retailer offering dynamic-price tariffs.
- Corner Live (Poland) — livestream shopping platform.
- BOOKR Kids (Hungary) — digital reading and literacy platform for children.
- Creem (Estonia) — payments, tax and invoicing infrastructure for software sellers.
- Immersion Labs (Poland) — VR, AR and AI-based training platform (MetaCoach).
- F13 (Poland) — Berlin-based developer of foundation models for SVG and vector graphics, founded by a Polish-born entrepreneur.
- Friendly Fire (Croatia) — franchise operator of gaming cafes, based in Zagreb.
- Occam Industries (Ukraine) — developer of autonomy software for drones.
- ForActive (Poland) — payment and client-management app for fitness professionals.
- Blackswan Space (Lithuania) — developer of autonomy tools for satellites.
- Embedd (Ukraine) — digital-twin software for chip design and verification.
- autoMEE (Poland) — AI-based accounting software (flowMEE).
- 1club (Bulgaria) — gym-management software.
- Veslo (Czech Republic) — point-of-sale and payments software for retail and hospitality, with offices in Prague and Bratislava.
- Nanogram (Bulgaria) — app for swiping through and playing user-made games.
- DOD Solution (Estonia) — developer of onboard AI for unmanned systems.
- CTHINGS.CO (Poland) — edge AI and IoT software provider, based in Warsaw.
- EnforceShield (Lithuania) — brand-protection software, with operations in Vilnius and Tennessee.
- Science 4 Beauty (Poland) — cosmetics developer using conotoxin-derived ingredients, based in Warsaw.
- Carebot (Czech Republic) — AI software for medical imaging analysis.
- VisionFlow (Slovakia) — Provider of video datasets for computer-vision models, based in Bratislava.
- TrueEngage (Poland) — web messaging and voice engagement solutions built on Genesys.
- InstArc (Estonia) — compliance-automation software for financial services.
- Sigvi (Lithuania) — car-rental service operating in Lithuania, Latvia and Poland.
- Plora.ai (Hungary) — developer of flexible robotic automation.
- Genesis Space Flight Laboratories (Croatia) — developer of reentry capsules, based in Cakovec.
- Hellobot (Poland) — AI voice agents for customer service, with offices in Wroclaw and Katowice.
- TesterArmy (Poland) — AI-based software quality-assurance testing.
- Astute (Serbia) — B2B new-media company.
- ElredoVoice (Czech Republic) — producer of AI-narrated audiobooks.
- Guideless (Lithuania) — AI platform that turns recorded workflows into step-by-step guides.
- Investly.pro (Poland) — platform offering digital-asset investment strategies, based in Warsaw.
- Talent Bridge (Poland) — psychometric assessment platform for recruitment, based in Warsaw.
- bilt.me (Estonia) — AI mobile-app builder that turns plain-language descriptions into native apps.
- Kyndred (Romania) — platform for building and interacting with AI characters.
- Trinity Robotics (Ukraine) — developer of ground robots for military logistics and evacuation tasks.
- display.dev (Estonia) — login-protected hosting for AI-generated files.
- semiQa (Poland) — developer of analog neural-network chips for AI, based in Wroclaw.
- DefendEye (Poland) — developer of AI-enabled detection drones, with offices in Miami and Krakow.
Outlook: what to expect for CEE in Q4 2026
Q3 followed the familiar pattern: a few large rounds drove the overall funding figures, while the rest of the market attracted approximately €327 million. Looking ahead, another potential mega-round could significantly influence Q4 results, but several other developments will be worth watching.
Five themes to watch in Q4 2026
- Will Q3 figures be revised upward?
Our Q3 data was compiled approximately three weeks after quarter-end, and smaller rounds are often disclosed with a delay. The number of recorded deals may therefore increase as new information becomes available. However, the impact on total funding is likely to be smaller, as the largest rounds have already been captured.
- Will Uforce close its $500 million round?
The Ukrainian-British drone manufacturer has reportedly been in talks to raise $500 million at a valuation of around $5 billion. If completed, the deal would be the largest in our five-quarter dataset, equivalent to approximately 70% of Q3's total funding. For now, the round remains unconfirmed.
- Will new defence funds write bigger checks?
Expeditions has closed its second fund at €197 million, while Resist.UA and Final Frontier are still fundraising. With disclosed defence and dual-use rounds remaining relatively small in Q3, it remains to be seen whether the new capital will translate into larger investments. We maintain our prediction of a €40 million-plus CEE defence round in Q4.
- Will CEE-founded companies continue raising capital abroad?
Six companies with CEE roots but headquartered in the US, UK, or Germany — Pathway, CUBE3 AI, FintechOS, Tiger Technology, Immersion Labs, and F13 — accounted for approximately €114 million, or 18% of Q3 funding. Their performance in the coming quarters will help show how much investment in CEE-founded businesses is flowing to companies based outside the region.
- Will CEE see a major exit?
According to BADideas.fund, CEE recorded 21 venture-backed exits in the first nine months of 2026, down from 38 a year earlier. While our dataset does not track exits, a major exit in Q4 could be an important signal for the region's VC ecosystem, particularly for funds looking to return capital to their investors.
Liquidity outlook
The IPO market remained active in Q3, with completed listings of ChangXin Memory, Enflame, Bending Spoons, Unitree, and Shein. Several large technology acquisitions were announced or agreed (see the global section for details on their status).
None of the transactions highlighted by Crunchbase involved a CEE company, while the regional data remains limited to the BADideas.fund’s count of 21 exits in the first nine months of 2026. We therefore can’t draw conclusions about CEE liquidity from global deals.
For CEE, M&A and secondary sales remain more likely routes to liquidity for mid-stage companies. Meanwhile, funds such as Orbit Capital's venture-debt vehicle provide additional financial options for companies that are not yet ready for exit.
Looking for secondary investors? Explore the full list of European VC players here.
Disclaimer: This report features VC rounds publicly disclosed before publication or shared by our VC and startup community. Grants, debt funding and transactions below €50,000 were not considered. While we value all startups operating in CEE, our totals count companies that were founded in CEE or maintain their primary operating base in the region - regardless of where their HQ sits today.
Sources: Vestbee VC & startup community, startup press releases, open data from web & social media sources, DaaS platforms such as Dealroom, PFR Ventures data on the Polish VC market, BADideas.fund.
If you have insights about the report, drop us a line!
Want a more detailed view of the CEE startup & VC ecosystem in Q3 2026? Discover our monthly, quarterly and yearly reports: